Sullivan
Microsoft has discontinued support for Internet Explorer. To access the Sullivan website, please install a modern browser like Microsoft Edge or Google Chrome.
Biography

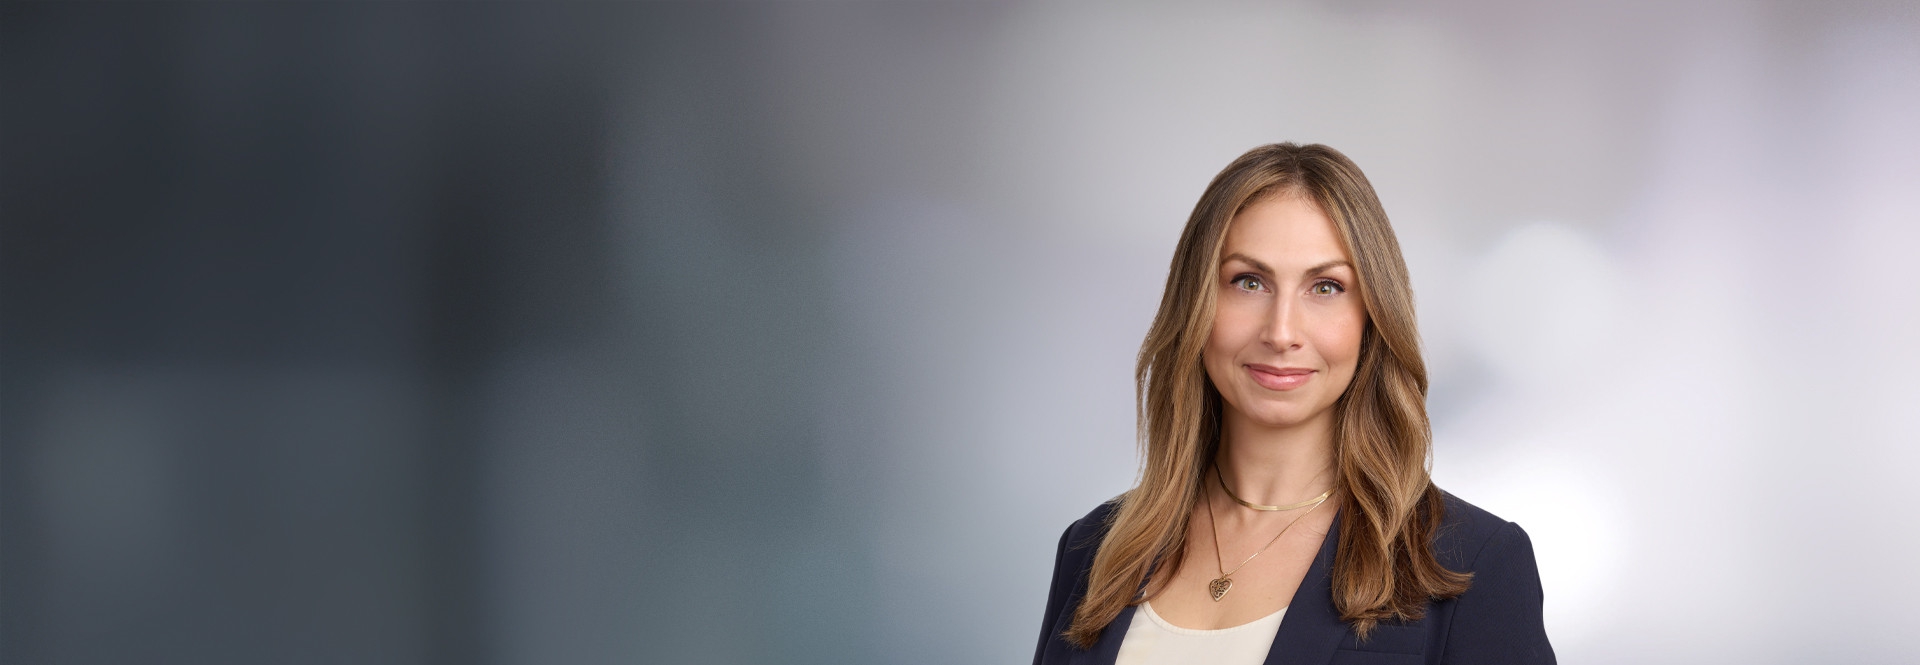
Natalie, a corporate partner, leads Sullivan's Fintech & Blockchain Group. She represents a diverse base of clients, including public and private companies, domestic and international, in a broad range of business and finance matters with a focus on cross-border mergers and acquisitions, securities law compliance, joint venture and financing transactions (including multi-jurisdictional trade and export finance transactions) and governance.

She represents companies across various industries, including finance, technology, media, energy, sports, healthcare, manufacturing and design. Additionally, Natalie has unique experience in advising dozens of blockchain and digital asset businesses of various sizes on complex regulatory challenges. She advises her clients in the formation and development of digital asset and cryptocurrency-based companies and technologies, on token, NFT and other digital asset sales, other generation and distribution events, and market infrastructure and exchange solutions on distributed ledger technology. She also counsels clients on domestic and cross-border cutting-edge distributed ledger and cryptocurrency, fintech and other consumer finance transactions.

Clients also benefit from Natalie's experience in litigating matters arising out of complex corporate and financial transactions and contractual disputes. Her IP experience includes preparing various intellectual property agreements (including purchases, assignments and licensing agreements), and she has counseled clients regarding selection and maintenance of trademarks, as well as copyright and domain name issues.

Natalie also currently serves as the Chair of Sullivan's Hiring Committee, and previously served as Director of Sullivan’s Summer Associate Program.

Prior to practicing law, Natalie was a financial consultant with Deloitte LLP in New York, advising national leadership on strategy initiatives, mergers and acquisitions.
Education
  • Benjamin N. Cardozo School of Law (J.D.)
  • University of Michigan (B.A., with distinction)
Bar & Court Admissions
  • New York
  • U.S. District Court, Eastern District of New York
  • U.S. District Court, Southern District of New York
  • England and Wales (Registered foreign lawyer)
Professional Qualifications
  • Director of Diversity and Inclusion for the American Bar Association Legal Opinions Committee
  • New York State Bar Association
Awards & Honors
  • Thomson Reuters "Stand-Out Lawyer" (2026)
  • "Ones to Watch," Best Lawyers in America®, Corporate Law (2024, 2025)
  • Ones to Watch," Best Lawyers in America®, Mergers & Acquisition Law (2021, 2022)
  • Recommended by The Legal 500 U.S. (2022-2026)
  • "Rising Star," New York Super Lawyers (2019-2022)
  • Leadership Council on Legal Diversity Fellows Program (2019)
Community Engagement
  • Advisory Board Member for Coalition for the Homeless First Step Program
Languages
  • French
Viewpoints
All Viewpoints
CFTC Outlines Contemplated Comprehensive Regulatory Framework for Retail Crypto Asset Transactions
On October 13, 2026, the Commodity Futures Trading Commission (the “CFTC”) issued an advance notice of contemplated rulemaking outlining two related initiatives concerning retail crypto asset transactions under Section 2(c)(2)(D) of the Commodity Exchange Act (the “CEA”). The first, referred to as Regulation CTX, sets out the CFTC’s preliminary interpretations of when crypto asset transactions are offered on a leveraged, margined or financed basis and when those transactions result in “actual delivery.” The second, referred to as Regulation CAM, describes a contemplated regulatory framework for trading venues and intermediaries handling covered transactions. If ultimately adopted substantially as contemplated, the initiatives could expand the circumstances in which crypto asset transactions are subject to federal commodities regulation and create a new regulatory pathway for crypto asset trading platforms seeking to operate under CFTC supervision. Background A Section 2(c)(2)(D) transaction is any transaction in a commodity that is both “(I) entered into with, or offered to (even if not entered with), a person that is not an eligible contract participant or eligible commercial entity" and "(II) entered into with, or offered to (even if not entered with), on a leveraged or margined basis, or financed by the offeror, the counterparty, or a person acting in concert with the offeror or counterparty on a similar basis.”  Unless an exception applies, Section 2(c)(2)(D) subjects such transactions to specified provisions of the CEA as if they were futures contracts and generally requires them to be conducted on or subject to the rules of a CFTC-regulated exchange. The CFTC contends that uncertainty surrounding the application of Section 2(c)(2)(D) to digital assets has impeded the migration of crypto trading activity to federally regulated markets.  According to the CFTC, retail market participants have instead relied primarily on state-level regulatory frameworks that were developed for money transmission activities rather than for trading markets.  The CFTC’s proposal seeks to replace that fragmented approach with a federal framework focused on market integrity, customer protection, transparency and risk management. Regulation CTX Regulation CTX, as described in the advance notice, contemplates a new comprehensive interpretation of how Section 2(c)(2)(D) applies to crypto asset transactions, following the CFTC’s withdrawal in 2025 of its prior interpretive guidance concerning actual delivery of digital assets. The advance notice focuses principally on two threshold issues: (a) when a transaction is deemed to be offered on a leveraged, margined or financed basis, and (b) when a crypto asset transaction is deemed to result in "actual delivery" sufficient to fall outside Section 2(c)(2)(D).  The advance notice reflects the CFTC's view that a broad range of crypto asset transactions currently conducted on spot trading platforms may fall within the scope of Section 2(c)(2)(D) and therefore may be subject to a federal regulatory framework comparable to that applicable to futures transactions. Broad Interpretation of "Offer" Perhaps the most consequential aspect of Regulation CTX is the CFTC's contemplated interpretation of what constitutes an "offer" of leverage, margin or financing. The CFTC preliminarily concludes that a transaction may become subject to Section 2(c)(2)(D) not only when leverage is actually utilized, but whenever a retail customer is offered the ability to obtain leverage, margin or financing, regardless of whether the customer ultimately elects to transact on a fully paid basis.  Thus, a covered offer may arise through a variety of customer-facing arrangements, including account opening documentation, exchange terms and conditions, margin agreements, financing programs and similar contractual arrangements that make leverage available to customers. The CFTC also suggests that financing arrangements offered through affiliated or coordinated third parties could trigger Section 2(c)(2)(D) treatment.  The CFTC also preliminarily concludes that financing offered by a third party may constitute a covered offer where the arrangement is facilitated, arranged, endorsed or materially assisted by the offeror or counterparty, including through marketing, influence over financing terms, revenue-sharing arrangements or integration with the offeror’s platform. Interpretation of the Actual Delivery Exception The advance notice also addresses the scope of the "actual delivery" exception in the context of in the application of Section 2(c)(2)(D) to digital assets.  The “actual delivery” exception excludes from Section 2(c)(2)(D) certain contracts that result in actual delivery and reflects typical cash market activity rather than the economic substance of an open futures contract.  In short, it reflects Congress’s intent not to interfere in the spot markets.  In the advance notice, the CFTC preliminarily concludes that actual delivery requires the customer to obtain a meaningful degree of possession or control over the purchased crypto asset. Depending on the asset and transaction, a meaningful degree of possession or control may require the customer to possess the credentials, such as private keys, associated with the relevant wallet address or account. Where an asset carries governance, staking or similar rights, the CFTC suggests that meaningful possession and control may also require the customer to exercise those rights directly and without material intermediary restrictions.  Under the CFTC’s preliminary interpretation, a fully paid, open CTX that remains reflected only through an exchange’s internal book-entry system would generally remain subject to Section 2(c)(2)(D) until actual delivery or another statutory exception applies. Continued Regulation of Fully Paid Positions The CFTC also takes the preliminary position that a fully paid crypto asset transaction may remain subject to Section 2(c)(2)(D) until actual delivery occurs. As a result, crypto assets held through an exchange's custodial or book-entry system, rather than transferred to a customer-controlled wallet, could remain within the scope of the CFTC's regulatory authority notwithstanding that the customer has paid the full purchase price.  Conversely, the CFTC acknowledges that many transactions executed through on-chain protocols may naturally satisfy the actual-delivery requirement because settlement occurs directly to customer-controlled wallets and results in the customer obtaining meaningful possession and control of the acquired assets.  Taken together, the contemplated interpretations of “offer,” “actual delivery” and fully paid positions would significantly broaden the circumstances in which crypto asset transactions may become subject to CFTC regulation. Regulation CAM Regulation CAM, as described in the advance notice, contemplates a new federal regulatory framework for crypto asset trading venues that offer transactions subject to Section 2(c)(2)(D). Rather than requiring digital asset platforms to fit within regulatory structures developed for traditional futures markets, the advance notice would create a specialized subset of designated contract market registration designed specifically for crypto asset transactions while preserving core principles relating to customer protection, financial integrity, market surveillance and risk management. Creation of a New Crypto Asset Market Registration Category Under the advance notice, a registered "Crypto Asset Market" ("CAM") would operate as a specialized form of designated contract market subject to modified regulatory requirements intended to accommodate the commercial realities of digital asset trading. The CFTC contemplates a framework that would permit, among other things, continuous 24-hour trading, integration of blockchain technologies into trading and market infrastructure, crypto-specific disclosure and surveillance requirements, specialized custody and operational standards, and the use of technology-enabled compliance controls. In developing the CAM framework, the CFTC repeatedly emphasizes the need to balance innovation and technological flexibility with traditional regulatory objectives such as customer protection, market transparency, prevention of manipulation and operational resilience. As currently contemplated, CTXs conducted on a CAM would be intermediated by an FCM and cleared and settled through a DCO, although the CAM, futures commission merchant (FCM) and derivatives clearing organization (DCO) functions could be performed by affiliated entities or, subject to appropriate registrations and safeguards, combined within a single integrated organization. Acceptance of Vertically Integrated Market Structures A particularly significant aspect of the advance notice is the CFTC’s willingness to accommodate vertically integrated business models that are commonly used in digital asset markets. Unlike traditional market structures that often separate trading, brokerage, custody and clearing functions among different regulated entities, the advance notice contemplates that a CAM could itself register as, or be affiliated with, a FCM and/or a DCO. Specialized Margin and Financing Framework The advance notice also would establish a framework for retail leveraged crypto asset transactions. Under the contemplated regime, retail customers would be permitted to obtain financing through arrangements administered by registered FCMs or qualifying banking institutions sponsored by FCMs. Those financing arrangements would serve as the basis for leveraged crypto asset transactions conducted on a CAM. Recognizing the volatility and operational characteristics of digital asset markets, the CFTC is considering a tailored margin regime rather than simply importing existing futures margin requirements. Among the subjects specifically identified for comment are continuously monitored margin systems, automated liquidation mechanisms, smart-contract-based risk management tools, standards governing acceptable collateral and rules addressing the treatment of customer assets securing financing arrangements. Custody, Customer Protection and Insolvency Issues The advance notice likewise devotes substantial attention to customer asset protection and raises numerous questions regarding how customer assets should be safeguarded within the CAM structure. In particular, the CFTC requests comment regarding customer asset segregation, rehypothecation practices, proof-of-reserves frameworks, custody arrangements, insolvency protections and the treatment of customer assets in the event of an intermediary bankruptcy.  The advance notice reflects the CFTC’s willingness to consider significant modifications to existing regulatory requirements governing exchange, brokerage, custody and clearing functions where necessary to accommodate the technological and operational characteristics of crypto asset markets, while preserving customer-protection, risk-management and market-integrity objectives. Sullivan Observations Convergence of Traditional and Digital Asset Market Infrastructure. The advance notice does not simply seek to regulate existing crypto trading activity.  Rather, it adapts core concepts of the CEA to digital asset markets, including exchange regulation, intermediary oversight, customer protections, clearing and margin requirements.  As a result, the advance notice may lower regulatory barriers for traditional financial institutions that have been reluctant to participate in digital asset markets while simultaneously imposing a more institutional regulatory framework on existing crypto market participants.   Expansion of CFTC Jurisdiction and Reorientation of Market Structure Regulation. Although framed as an interpretive and rulemaking initiative, the advance notice would significantly expand the practical reach of the CFTC's authority over crypto asset markets. The contemplated interpretations of "offer" and "actual delivery" would subject many transactions that market participants have historically viewed as spot transactions to a federal regulatory framework under Section 2(c)(2)(D). More broadly, the advance notice reflects the CFTC’s view that covered trading activity should operate within a uniform federal market-structure regime, rather than remain principally dependent on state money-transmission and crypto-asset licensing frameworks. The precise extent to which federal regulation would displace particular state-law requirements, however, remains to be developed.   Part of a Broader SEC-CFTC Digital Asset Regulatory Framework. The advance notice should not be viewed in isolation. Throughout the release, the CFTC repeatedly situates Regulation CTX and Regulation CAM within a broader federal effort, undertaken jointly with the SEC, to establish a comprehensive regulatory framework for digital asset markets. The advance notice builds on the agencies' March 2026 Joint Crypto Asset Taxonomy, the SEC-CFTC memorandum of understanding regarding digital asset regulation, and the SEC's contemplated Regulation Crypto Assets (91 Fed. Reg. 54510, August 21, 2026) all of which are intended to provide greater clarity regarding the regulatory treatment of crypto assets and secondary market trading. The advance notice also reflects an increasingly consistent regulatory focus on customer asset protection and custody arrangements. While operating under different statutory frameworks, the SEC and the CFTC are examining issues such as custody, customer asset segregation, intermediary insolvency, and the safeguarding of digital assets held for customers. (See Sullivan Client Alert SEC Proposes New Crypto Custody Framework for Registered Investment Advisers and Regulated Funds.)  Market participants should expect continued regulatory scrutiny of trading, custody, financing and clearing arrangements, particularly where a single platform performs multiple functions within the digital asset ecosystem.   Potential Impact on Existing Market Structures. The advance notice may require digital asset exchanges, custodians, lenders, broker-dealers and other market participants to reevaluate custody arrangements, wallet structures, financing programs, customer onboarding documentation and affiliated business models. Platforms that offer margin or financing features may find that transactions historically viewed as spot transactions become subject to CFTC regulation unless actual delivery occurs, while integrated trading, custody and financing arrangements may face increased regulatory scrutiny. What Comes Next Public comment of the advance notice closes December 14, 2026.  As the advance notice does not contain contemplated regulatory text and leaves many central elements of both initiatives open for comment, the CFTC would need to undertake additional notice-and-comment rulemaking before adopting binding Regulation CTX or Regulation CAM requirements. For More Information This Client Alert has been prepared by John Hunt, a Partner in the Investment Management practice group, and Natalie Lederman, a Partner in and Leader of the Fintech & Blockchain practice group, of the international law firm of Sullivan & Worcester LLP.  For more information, Mr. Hunt may be reached in our Boston office by calling +1 (617) 338-2961 or our London office by calling +44 (0)20 7448 1000, or by email at jhunt@sullivanlaw.com. Ms. Lederman may be reached in our New York office by calling +1 (212) 660-3039 or by email at nlederman@sullivanlaw.com. This Client Alert is provided for general informational purposes only and does not constitute legal advice.
Breaking: FinCEN Removes BOI Reporting Requirements for U.S. Companies and U.S. Persons
The U.S. Department of the Treasury’s Financial Crimes Enforcement Network (FinCEN) announced, on March 21, 2025, that it issued an interim final rule that removes the requirements for U.S. companies and U.S. persons to report beneficial ownership information (BOI) under the Corporate Transparency Act (CTA). The interim final rule narrows the existing BOI reporting requirements by revising the definition of “reporting company” (i.e., companies required to file BOI reports) to include only “foreign reporting companies” (i.e., companies formed outside of a US state or tribal territory but that are registered to do business in the United States). As a result, domestic reporting companies (i.e., companies formed in a US state or tribal territory) are now exempted from the BOI reporting requirements pursuant to the CTA. The rule also provides foreign reporting companies with exemptions from reporting any U.S. persons who are beneficial owners of the foreign reporting company. Foreign reporting companies that are registered to do business in the United States must file BOI reports with FinCEN within 30 days from the date of the rule’s publication in the Federal Register on March 26, 2025. If foreign reporting companies are registered to do business in the United States on or after the date of publication, they must submit BOI reports within 30 days after receiving notice of the effectiveness of their registration. Please see our prior CTA-related client alerts here and here for additional information about the filing requirements and the applicable exceptions, and do not hesitate to reach out to your contacts at Sullivan if you have any questions about CTA compliance or BOI report filing requirements.
Sullivan Advises BAFT and ITFA on Updated CRR Legal Opinions for the 2008 English Law Master Participation Agreement (MPA)
(London and New York) – Sullivan has advised BAFT (the Bankers Association for Finance & Trade) and ITFA (the International Trade and Forfaiting Association) on the publication of the two Capital Requirements Regulation (CRR) legal opinions covering the 2008 English law Master Participation Agreement (MPA). The newly released opinions comprise the EU CRR opinion on English law MPA 2008 and the UK CRR opinion on English law MPA 2008. They are intended for institutions that continue to use the 2008 version of the MPA, having executed it prior to the introduction of the later versions. The publication of these two legal opinions completes the suite of updated CRR legal opinions that Sullivan has prepared for BAFT and ITFA, following the release of the updated opinions covering the other English law MPAs, New York law MPAs and the Surety MPAs earlier this year, which can be read in full, here. Importantly, these opinions note that eligibility for credit risk mitigation (CRM) may only apply if the Participant shares in the fraud risk in the optional wording of Clause 11. As the 2008 English law MPA has long since been superseded, ITFA has announced that these are the final legal opinions that will be issued in respect of that document, reflecting both the age of the underlying template and the increasing difficulty of providing a clean opinion where one of the optional wordings is adopted. Geoffrey Wynne, head of Sullivan’s Trade & Export Finance Group, commented: “We are pleased to have continued our long-standing work with BAFT and ITFA advising on these CRR legal opinions for the 2008 English law MPA. Their publication completes the current suite of opinions available to members and provides support for institutions that continue to use the earlier version of the agreement. It is hoped that institutions will pay heed to reservations and react accordingly.” The Sullivan team advising BAFT and ITFA includes partners Geoffrey Wynne and Marian Boyle in London and partner Natalie Lederman in New York. About Sullivan Sullivan & Worcester (Sullivan) is a global law firm with lawyers in Boston, London, New York, Tel Aviv and Washington, D.C. Sullivan’s clients, including Fortune 500 companies, leading financial services firms and asset managers, boards of directors and emerging businesses, rely on Sullivan’s ability to navigate complex legal and operational landscapes and its commitment to best in class client service. For further information, please visit the firm’s website and LinkedIn.
Top Tier Firm, Legal 500 United States 2026
Sullivan & Worcester Ranked in the Legal 500 United States 2026 Edition
Boston, MA – Sullivan & Worcester announced that its practice groups and attorneys have been ranked and recommended in the Legal 500 United States 2026. The firm’s Real Estate practice was newly ranked Tier 1 in the “Real estate – mid-market ($0-500m)” category and the firm maintained rankings across a variety of practice areas. Partners Nicole Crum and John Steiner were newly ranked as Leading Partners and Ryan Rosenblatt as a Next Generation Partner. Peers and more than 300,000 corporate counsel were surveyed and interviewed globally in the past 12 months to assess law firms’ overall visibility and reputation, culminating in detailed rankings and editorial. The Legal 500 is an independent guide, and firms and individuals are recommended purely on merit. Sullivan's lawyers received the following rankings: Leading Partners: The Legal 500’s Guide to Outstanding Lawyers Nationwide Benjamin Armour - M&A: Middle-Market (Sub-$500m); M&A: middle-market ($0-250m) Ameek Ashok Ponda - Real Estate Investment Trusts (REITs)  Nicole Crum - Mutual/registered/exchange-traded funds Lewis Segall - M&A: Middle-Market (Sub-$500m); M&A: middle-market ($0-250m) John Steiner - Real estate – mid-market ($0-500m) Douglas Stransky - International Tax Joel Telpner - Fintech Next Generation Partners: The Legal 500’s Guide to Up-and-Coming Lawyers Nationwide Ryan Rosenblatt - General commercial disputes – mid-market ($250-500m) Sarah Wellings - Real Estate Investment Trusts (REITs) Practice Areas Ranked and Attorneys Recognized Corporate Governance “Our lead partner, Nicole Crum, who leads the investment industry practice, is exceptional. She demonstrates strong industry knowledge yet is very personable and anticipates what we need to know or what we should consider doing to handle any matter. The team roll up their sleeves and provide recommendations as to how we as a board should handle any matter. Strong service commitment and work ethic!” “The team we have at Sullivan & Worcester has served our company for years and knows the management team, staff as well as our board members. They are extremely responsive and proactive and anticipate what we should be aware of, concerned about, excited about, and how to handle oversight, processes and protocols to ensure we are carrying out our fiduciary duties. The partners are experts in this industry.” Leading Partner: Nicole Crum Recommended Lawyers: Howard Berkenblit, David Leahy Dispute Resolution/General Commercial Disputes “Diverse skillset. Client centric. Transparency. Urgency provided on all matters.” “I have worked with Gerry Silver for over 15 years and have found his pragmatic approach to complex matters refreshing. He understands our business, culture and market, and will give me his opinion in a digestible manner.” Next Generation Partner: Ryan Rosenblatt Recommended Lawyers: Gerry Silver, Patrick Dinardo, Laura Steinberg, Michael Sullivan, Amy Zuccarello, Erika Todd, Christopher Shields, Anna Lea McNerney Employee Benefits, Executive Compensation and Retirement Plans: Design “The level of expertise is top shelf. David Guadagnoli seems to know all of ERISA and IRS rulings.” “David Guadagnoli and Amy Sheridan both have superior knowledge in their respective areas. I value the ability to raise issues whether simple or complex. The firm takes the same diligent approach across all spectrums of complexity.” Recommended Lawyers: David Guadagnoli, Amy Sheridan Environment: Transactional Fintech “Sullivan & Worcester is one of the finest firms with which I have worked.” “The lawyers are excellent, and the firm consistently provides the highest quality of customer service.” Leading Partner: Joel Telpner Recommended Lawyers: Natalie Lederman, Benjamin Armour, Scott Kaufman, Harvey Bines, Christopher Curtis Land Use/Zoning Recommended Lawyers: Gregory Sampson, Ashley Brooks, Victor Baltera, Karen Kepler, Ashley Tan M&A: Corporate and Commercial: Venture Capital and Emerging Companies Recommended Lawyers: Scott Kaufman, Lewis Segall, Benjamin Armour, Michael Student M&A: Middle-Market ($0-250m) “The partner Lewis Segall has been working with our company for 15 years and we have a good working relationship with him. He knows our history and very attentive to our needs.” “Lewis Segall is very attentive to our needs. We very much value him.” Leading Partners: Benjamin Armour, Lewis Segall Recommended Lawyers: Natalie Lederman Mutual/Registered/Exchange-Traded Funds “Sullivan & Worcester's practice is defined by its deep expertise in investment funds and its ability to deliver clear, commercially grounded advice across the full fund lifecycle—from formation and structuring to regulatory compliance and complex transactions.” “The team is highly experienced, collaborative, and excel in efficient execution and clear communication.” Leading Partner: Nicole Crum Recommended Lawyers: David Leahy, David Mahaffey, Rachael Schwartz Real Estate Leading Partner: John Steiner Recommended Lawyers: Ashley Brooks, Karen Kepler, Gregory Sampson, Sharon Leifer, Louis Monti, Spencer Stone, Ashley Tan Real Estate Investment Trusts (REITs) “We have built multiple complex and sophisticated REIT platforms over the years and worked with many top-tier REIT specialists, but Sullivan’s REIT practice is by far the best, with Sarah Wellings.” Leading Partner: Ameek Ashok Ponda Next Generation Partner: Sarah Wellings Recommended Lawyers: Angela Gomes, Louis Monti, Shu Wei, Cameron Cosby International Tax “The international collaboration with S&W is exceptional.” “What really stands out is their willingness to engage, openness to different ideas and opinions, clearly expressed expectations, and clients' objectives.” Leading Partner: Douglas Stransky Recommended Lawyers: Lewis Greenwald, Eric Rietveld Tax > US Taxes: Contentious Recommended Lawyers: Richard Jones, David Nagle, Daniel Ryan, Caroline Kupiec Tax > US Taxes: Non-Contentious “Sarah Wellings is, quite simply, the best lawyer we have ever worked with. Her expertise extends far beyond tax and REIT matters, encompassing governance, financing, and complex commercial issues. Decades of experience and technical mastery make her an indispensable partner. Sarah is our central point of contact who makes everything seamless. Her in-house counsel background gives her a unique client perspective: she anticipates needs, solves problems before they arise, and delivers concise, well-structured updates that simplify even the most intricate issues. She coordinates effortlessly with all parties involved. Her judgment is exceptional. Sarah strikes the perfect balance between comprehensive academic rigor and practical, business-oriented advice. She combines technical REIT/tax excellence with commercial instincts, ensuring every recommendation is both legally sound and strategically smart. Her ability to translate complex law into clear, actionable guidance is unmatched. Sarah is incredibly responsive without ever sacrificing quality. She treats our matters as her own, demonstrating a rare ownership mindset and collaborative spirit. Her integrity is uncompromising, giving us absolute confidence in her counsel. In short, Sarah Wellings defines legal excellence: reliable, commercially minded, and client-focused. Working with her feels like being in the safest possible hands; she consistently exceeds expectations and orchestrates complex transactions with clarity and precision.” Recommended Lawyers: Ameek Ashok Ponda, Richard Jones, Douglas Stransky, Sarah Wellings About Sullivan Sullivan & Worcester (Sullivan) is a premier international law firm with lawyers in Boston, London, New York, Tel Aviv and Washington, D.C. Sullivan’s clients, including Fortune 500 companies, leading financial services firms and asset managers, boards of directors, real estate companies, and emerging businesses, rely on Sullivan’s ability to navigate complex legal and operational landscapes, the impeccable judgment of its lawyers, and its commitment to best-in-class client service.

Natalie S. Lederman

Natalie, a corporate partner, leads Sullivan's Fintech & Blockchain Group. She represents a diverse base of clients, including public and private companies, domestic and international, in a broad range of business and finance matters with a focus on cross-border mergers and acquisitions, securities law compliance, joint venture and financing transactions (including multi-jurisdictional trade and export finance transactions) and governance.

She represents companies across various industries, including finance, technology, media, energy, sports, healthcare, manufacturing and design. Additionally, Natalie has unique experience in advising dozens of blockchain and digital asset businesses of various sizes on complex regulatory challenges. She advises her clients in the formation and development of digital asset and cryptocurrency-based companies and technologies, on token, NFT and other digital asset sales, other generation and distribution events, and market infrastructure and exchange solutions on distributed ledger technology. She also counsels clients on domestic and cross-border cutting-edge distributed ledger and cryptocurrency, fintech and other consumer finance transactions.

Clients also benefit from Natalie's experience in litigating matters arising out of complex corporate and financial transactions and contractual disputes. Her IP experience includes preparing various intellectual property agreements (including purchases, assignments and licensing agreements), and she has counseled clients regarding selection and maintenance of trademarks, as well as copyright and domain name issues.

Natalie also currently serves as the Chair of Sullivan's Hiring Committee, and previously served as Director of Sullivan’s Summer Associate Program.

Prior to practicing law, Natalie was a financial consultant with Deloitte LLP in New York, advising national leadership on strategy initiatives, mergers and acquisitions.

Viewpoints
All Viewpoints
CFTC Outlines Contemplated Comprehensive Regulatory Framework for Retail Crypto Asset Transactions
On October 13, 2026, the Commodity Futures Trading Commission (the “CFTC”) issued an advance notice of contemplated rulemaking outlining two related initiatives concerning retail crypto asset transactions under Section 2(c)(2)(D) of the Commodity Exchange Act (the “CEA”). The first, referred to as Regulation CTX, sets out the CFTC’s preliminary interpretations of when crypto asset transactions are offered on a leveraged, margined or financed basis and when those transactions result in “actual delivery.” The second, referred to as Regulation CAM, describes a contemplated regulatory framework for trading venues and intermediaries handling covered transactions. If ultimately adopted substantially as contemplated, the initiatives could expand the circumstances in which crypto asset transactions are subject to federal commodities regulation and create a new regulatory pathway for crypto asset trading platforms seeking to operate under CFTC supervision. Background A Section 2(c)(2)(D) transaction is any transaction in a commodity that is both “(I) entered into with, or offered to (even if not entered with), a person that is not an eligible contract participant or eligible commercial entity" and "(II) entered into with, or offered to (even if not entered with), on a leveraged or margined basis, or financed by the offeror, the counterparty, or a person acting in concert with the offeror or counterparty on a similar basis.”  Unless an exception applies, Section 2(c)(2)(D) subjects such transactions to specified provisions of the CEA as if they were futures contracts and generally requires them to be conducted on or subject to the rules of a CFTC-regulated exchange. The CFTC contends that uncertainty surrounding the application of Section 2(c)(2)(D) to digital assets has impeded the migration of crypto trading activity to federally regulated markets.  According to the CFTC, retail market participants have instead relied primarily on state-level regulatory frameworks that were developed for money transmission activities rather than for trading markets.  The CFTC’s proposal seeks to replace that fragmented approach with a federal framework focused on market integrity, customer protection, transparency and risk management. Regulation CTX Regulation CTX, as described in the advance notice, contemplates a new comprehensive interpretation of how Section 2(c)(2)(D) applies to crypto asset transactions, following the CFTC’s withdrawal in 2025 of its prior interpretive guidance concerning actual delivery of digital assets. The advance notice focuses principally on two threshold issues: (a) when a transaction is deemed to be offered on a leveraged, margined or financed basis, and (b) when a crypto asset transaction is deemed to result in "actual delivery" sufficient to fall outside Section 2(c)(2)(D).  The advance notice reflects the CFTC's view that a broad range of crypto asset transactions currently conducted on spot trading platforms may fall within the scope of Section 2(c)(2)(D) and therefore may be subject to a federal regulatory framework comparable to that applicable to futures transactions. Broad Interpretation of "Offer" Perhaps the most consequential aspect of Regulation CTX is the CFTC's contemplated interpretation of what constitutes an "offer" of leverage, margin or financing. The CFTC preliminarily concludes that a transaction may become subject to Section 2(c)(2)(D) not only when leverage is actually utilized, but whenever a retail customer is offered the ability to obtain leverage, margin or financing, regardless of whether the customer ultimately elects to transact on a fully paid basis.  Thus, a covered offer may arise through a variety of customer-facing arrangements, including account opening documentation, exchange terms and conditions, margin agreements, financing programs and similar contractual arrangements that make leverage available to customers. The CFTC also suggests that financing arrangements offered through affiliated or coordinated third parties could trigger Section 2(c)(2)(D) treatment.  The CFTC also preliminarily concludes that financing offered by a third party may constitute a covered offer where the arrangement is facilitated, arranged, endorsed or materially assisted by the offeror or counterparty, including through marketing, influence over financing terms, revenue-sharing arrangements or integration with the offeror’s platform. Interpretation of the Actual Delivery Exception The advance notice also addresses the scope of the "actual delivery" exception in the context of in the application of Section 2(c)(2)(D) to digital assets.  The “actual delivery” exception excludes from Section 2(c)(2)(D) certain contracts that result in actual delivery and reflects typical cash market activity rather than the economic substance of an open futures contract.  In short, it reflects Congress’s intent not to interfere in the spot markets.  In the advance notice, the CFTC preliminarily concludes that actual delivery requires the customer to obtain a meaningful degree of possession or control over the purchased crypto asset. Depending on the asset and transaction, a meaningful degree of possession or control may require the customer to possess the credentials, such as private keys, associated with the relevant wallet address or account. Where an asset carries governance, staking or similar rights, the CFTC suggests that meaningful possession and control may also require the customer to exercise those rights directly and without material intermediary restrictions.  Under the CFTC’s preliminary interpretation, a fully paid, open CTX that remains reflected only through an exchange’s internal book-entry system would generally remain subject to Section 2(c)(2)(D) until actual delivery or another statutory exception applies. Continued Regulation of Fully Paid Positions The CFTC also takes the preliminary position that a fully paid crypto asset transaction may remain subject to Section 2(c)(2)(D) until actual delivery occurs. As a result, crypto assets held through an exchange's custodial or book-entry system, rather than transferred to a customer-controlled wallet, could remain within the scope of the CFTC's regulatory authority notwithstanding that the customer has paid the full purchase price.  Conversely, the CFTC acknowledges that many transactions executed through on-chain protocols may naturally satisfy the actual-delivery requirement because settlement occurs directly to customer-controlled wallets and results in the customer obtaining meaningful possession and control of the acquired assets.  Taken together, the contemplated interpretations of “offer,” “actual delivery” and fully paid positions would significantly broaden the circumstances in which crypto asset transactions may become subject to CFTC regulation. Regulation CAM Regulation CAM, as described in the advance notice, contemplates a new federal regulatory framework for crypto asset trading venues that offer transactions subject to Section 2(c)(2)(D). Rather than requiring digital asset platforms to fit within regulatory structures developed for traditional futures markets, the advance notice would create a specialized subset of designated contract market registration designed specifically for crypto asset transactions while preserving core principles relating to customer protection, financial integrity, market surveillance and risk management. Creation of a New Crypto Asset Market Registration Category Under the advance notice, a registered "Crypto Asset Market" ("CAM") would operate as a specialized form of designated contract market subject to modified regulatory requirements intended to accommodate the commercial realities of digital asset trading. The CFTC contemplates a framework that would permit, among other things, continuous 24-hour trading, integration of blockchain technologies into trading and market infrastructure, crypto-specific disclosure and surveillance requirements, specialized custody and operational standards, and the use of technology-enabled compliance controls. In developing the CAM framework, the CFTC repeatedly emphasizes the need to balance innovation and technological flexibility with traditional regulatory objectives such as customer protection, market transparency, prevention of manipulation and operational resilience. As currently contemplated, CTXs conducted on a CAM would be intermediated by an FCM and cleared and settled through a DCO, although the CAM, futures commission merchant (FCM) and derivatives clearing organization (DCO) functions could be performed by affiliated entities or, subject to appropriate registrations and safeguards, combined within a single integrated organization. Acceptance of Vertically Integrated Market Structures A particularly significant aspect of the advance notice is the CFTC’s willingness to accommodate vertically integrated business models that are commonly used in digital asset markets. Unlike traditional market structures that often separate trading, brokerage, custody and clearing functions among different regulated entities, the advance notice contemplates that a CAM could itself register as, or be affiliated with, a FCM and/or a DCO. Specialized Margin and Financing Framework The advance notice also would establish a framework for retail leveraged crypto asset transactions. Under the contemplated regime, retail customers would be permitted to obtain financing through arrangements administered by registered FCMs or qualifying banking institutions sponsored by FCMs. Those financing arrangements would serve as the basis for leveraged crypto asset transactions conducted on a CAM. Recognizing the volatility and operational characteristics of digital asset markets, the CFTC is considering a tailored margin regime rather than simply importing existing futures margin requirements. Among the subjects specifically identified for comment are continuously monitored margin systems, automated liquidation mechanisms, smart-contract-based risk management tools, standards governing acceptable collateral and rules addressing the treatment of customer assets securing financing arrangements. Custody, Customer Protection and Insolvency Issues The advance notice likewise devotes substantial attention to customer asset protection and raises numerous questions regarding how customer assets should be safeguarded within the CAM structure. In particular, the CFTC requests comment regarding customer asset segregation, rehypothecation practices, proof-of-reserves frameworks, custody arrangements, insolvency protections and the treatment of customer assets in the event of an intermediary bankruptcy.  The advance notice reflects the CFTC’s willingness to consider significant modifications to existing regulatory requirements governing exchange, brokerage, custody and clearing functions where necessary to accommodate the technological and operational characteristics of crypto asset markets, while preserving customer-protection, risk-management and market-integrity objectives. Sullivan Observations Convergence of Traditional and Digital Asset Market Infrastructure. The advance notice does not simply seek to regulate existing crypto trading activity.  Rather, it adapts core concepts of the CEA to digital asset markets, including exchange regulation, intermediary oversight, customer protections, clearing and margin requirements.  As a result, the advance notice may lower regulatory barriers for traditional financial institutions that have been reluctant to participate in digital asset markets while simultaneously imposing a more institutional regulatory framework on existing crypto market participants.   Expansion of CFTC Jurisdiction and Reorientation of Market Structure Regulation. Although framed as an interpretive and rulemaking initiative, the advance notice would significantly expand the practical reach of the CFTC's authority over crypto asset markets. The contemplated interpretations of "offer" and "actual delivery" would subject many transactions that market participants have historically viewed as spot transactions to a federal regulatory framework under Section 2(c)(2)(D). More broadly, the advance notice reflects the CFTC’s view that covered trading activity should operate within a uniform federal market-structure regime, rather than remain principally dependent on state money-transmission and crypto-asset licensing frameworks. The precise extent to which federal regulation would displace particular state-law requirements, however, remains to be developed.   Part of a Broader SEC-CFTC Digital Asset Regulatory Framework. The advance notice should not be viewed in isolation. Throughout the release, the CFTC repeatedly situates Regulation CTX and Regulation CAM within a broader federal effort, undertaken jointly with the SEC, to establish a comprehensive regulatory framework for digital asset markets. The advance notice builds on the agencies' March 2026 Joint Crypto Asset Taxonomy, the SEC-CFTC memorandum of understanding regarding digital asset regulation, and the SEC's contemplated Regulation Crypto Assets (91 Fed. Reg. 54510, August 21, 2026) all of which are intended to provide greater clarity regarding the regulatory treatment of crypto assets and secondary market trading. The advance notice also reflects an increasingly consistent regulatory focus on customer asset protection and custody arrangements. While operating under different statutory frameworks, the SEC and the CFTC are examining issues such as custody, customer asset segregation, intermediary insolvency, and the safeguarding of digital assets held for customers. (See Sullivan Client Alert SEC Proposes New Crypto Custody Framework for Registered Investment Advisers and Regulated Funds.)  Market participants should expect continued regulatory scrutiny of trading, custody, financing and clearing arrangements, particularly where a single platform performs multiple functions within the digital asset ecosystem.   Potential Impact on Existing Market Structures. The advance notice may require digital asset exchanges, custodians, lenders, broker-dealers and other market participants to reevaluate custody arrangements, wallet structures, financing programs, customer onboarding documentation and affiliated business models. Platforms that offer margin or financing features may find that transactions historically viewed as spot transactions become subject to CFTC regulation unless actual delivery occurs, while integrated trading, custody and financing arrangements may face increased regulatory scrutiny. What Comes Next Public comment of the advance notice closes December 14, 2026.  As the advance notice does not contain contemplated regulatory text and leaves many central elements of both initiatives open for comment, the CFTC would need to undertake additional notice-and-comment rulemaking before adopting binding Regulation CTX or Regulation CAM requirements. For More Information This Client Alert has been prepared by John Hunt, a Partner in the Investment Management practice group, and Natalie Lederman, a Partner in and Leader of the Fintech & Blockchain practice group, of the international law firm of Sullivan & Worcester LLP.  For more information, Mr. Hunt may be reached in our Boston office by calling +1 (617) 338-2961 or our London office by calling +44 (0)20 7448 1000, or by email at jhunt@sullivanlaw.com. Ms. Lederman may be reached in our New York office by calling +1 (212) 660-3039 or by email at nlederman@sullivanlaw.com. This Client Alert is provided for general informational purposes only and does not constitute legal advice.
Breaking: FinCEN Removes BOI Reporting Requirements for U.S. Companies and U.S. Persons
The U.S. Department of the Treasury’s Financial Crimes Enforcement Network (FinCEN) announced, on March 21, 2025, that it issued an interim final rule that removes the requirements for U.S. companies and U.S. persons to report beneficial ownership information (BOI) under the Corporate Transparency Act (CTA). The interim final rule narrows the existing BOI reporting requirements by revising the definition of “reporting company” (i.e., companies required to file BOI reports) to include only “foreign reporting companies” (i.e., companies formed outside of a US state or tribal territory but that are registered to do business in the United States). As a result, domestic reporting companies (i.e., companies formed in a US state or tribal territory) are now exempted from the BOI reporting requirements pursuant to the CTA. The rule also provides foreign reporting companies with exemptions from reporting any U.S. persons who are beneficial owners of the foreign reporting company. Foreign reporting companies that are registered to do business in the United States must file BOI reports with FinCEN within 30 days from the date of the rule’s publication in the Federal Register on March 26, 2025. If foreign reporting companies are registered to do business in the United States on or after the date of publication, they must submit BOI reports within 30 days after receiving notice of the effectiveness of their registration. Please see our prior CTA-related client alerts here and here for additional information about the filing requirements and the applicable exceptions, and do not hesitate to reach out to your contacts at Sullivan if you have any questions about CTA compliance or BOI report filing requirements.
Sullivan Advises BAFT and ITFA on Updated CRR Legal Opinions for the 2008 English Law Master Participation Agreement (MPA)
(London and New York) – Sullivan has advised BAFT (the Bankers Association for Finance & Trade) and ITFA (the International Trade and Forfaiting Association) on the publication of the two Capital Requirements Regulation (CRR) legal opinions covering the 2008 English law Master Participation Agreement (MPA). The newly released opinions comprise the EU CRR opinion on English law MPA 2008 and the UK CRR opinion on English law MPA 2008. They are intended for institutions that continue to use the 2008 version of the MPA, having executed it prior to the introduction of the later versions. The publication of these two legal opinions completes the suite of updated CRR legal opinions that Sullivan has prepared for BAFT and ITFA, following the release of the updated opinions covering the other English law MPAs, New York law MPAs and the Surety MPAs earlier this year, which can be read in full, here. Importantly, these opinions note that eligibility for credit risk mitigation (CRM) may only apply if the Participant shares in the fraud risk in the optional wording of Clause 11. As the 2008 English law MPA has long since been superseded, ITFA has announced that these are the final legal opinions that will be issued in respect of that document, reflecting both the age of the underlying template and the increasing difficulty of providing a clean opinion where one of the optional wordings is adopted. Geoffrey Wynne, head of Sullivan’s Trade & Export Finance Group, commented: “We are pleased to have continued our long-standing work with BAFT and ITFA advising on these CRR legal opinions for the 2008 English law MPA. Their publication completes the current suite of opinions available to members and provides support for institutions that continue to use the earlier version of the agreement. It is hoped that institutions will pay heed to reservations and react accordingly.” The Sullivan team advising BAFT and ITFA includes partners Geoffrey Wynne and Marian Boyle in London and partner Natalie Lederman in New York. About Sullivan Sullivan & Worcester (Sullivan) is a global law firm with lawyers in Boston, London, New York, Tel Aviv and Washington, D.C. Sullivan’s clients, including Fortune 500 companies, leading financial services firms and asset managers, boards of directors and emerging businesses, rely on Sullivan’s ability to navigate complex legal and operational landscapes and its commitment to best in class client service. For further information, please visit the firm’s website and LinkedIn.
Top Tier Firm, Legal 500 United States 2026
Sullivan & Worcester Ranked in the Legal 500 United States 2026 Edition
Boston, MA – Sullivan & Worcester announced that its practice groups and attorneys have been ranked and recommended in the Legal 500 United States 2026. The firm’s Real Estate practice was newly ranked Tier 1 in the “Real estate – mid-market ($0-500m)” category and the firm maintained rankings across a variety of practice areas. Partners Nicole Crum and John Steiner were newly ranked as Leading Partners and Ryan Rosenblatt as a Next Generation Partner. Peers and more than 300,000 corporate counsel were surveyed and interviewed globally in the past 12 months to assess law firms’ overall visibility and reputation, culminating in detailed rankings and editorial. The Legal 500 is an independent guide, and firms and individuals are recommended purely on merit. Sullivan's lawyers received the following rankings: Leading Partners: The Legal 500’s Guide to Outstanding Lawyers Nationwide Benjamin Armour - M&A: Middle-Market (Sub-$500m); M&A: middle-market ($0-250m) Ameek Ashok Ponda - Real Estate Investment Trusts (REITs)  Nicole Crum - Mutual/registered/exchange-traded funds Lewis Segall - M&A: Middle-Market (Sub-$500m); M&A: middle-market ($0-250m) John Steiner - Real estate – mid-market ($0-500m) Douglas Stransky - International Tax Joel Telpner - Fintech Next Generation Partners: The Legal 500’s Guide to Up-and-Coming Lawyers Nationwide Ryan Rosenblatt - General commercial disputes – mid-market ($250-500m) Sarah Wellings - Real Estate Investment Trusts (REITs) Practice Areas Ranked and Attorneys Recognized Corporate Governance “Our lead partner, Nicole Crum, who leads the investment industry practice, is exceptional. She demonstrates strong industry knowledge yet is very personable and anticipates what we need to know or what we should consider doing to handle any matter. The team roll up their sleeves and provide recommendations as to how we as a board should handle any matter. Strong service commitment and work ethic!” “The team we have at Sullivan & Worcester has served our company for years and knows the management team, staff as well as our board members. They are extremely responsive and proactive and anticipate what we should be aware of, concerned about, excited about, and how to handle oversight, processes and protocols to ensure we are carrying out our fiduciary duties. The partners are experts in this industry.” Leading Partner: Nicole Crum Recommended Lawyers: Howard Berkenblit, David Leahy Dispute Resolution/General Commercial Disputes “Diverse skillset. Client centric. Transparency. Urgency provided on all matters.” “I have worked with Gerry Silver for over 15 years and have found his pragmatic approach to complex matters refreshing. He understands our business, culture and market, and will give me his opinion in a digestible manner.” Next Generation Partner: Ryan Rosenblatt Recommended Lawyers: Gerry Silver, Patrick Dinardo, Laura Steinberg, Michael Sullivan, Amy Zuccarello, Erika Todd, Christopher Shields, Anna Lea McNerney Employee Benefits, Executive Compensation and Retirement Plans: Design “The level of expertise is top shelf. David Guadagnoli seems to know all of ERISA and IRS rulings.” “David Guadagnoli and Amy Sheridan both have superior knowledge in their respective areas. I value the ability to raise issues whether simple or complex. The firm takes the same diligent approach across all spectrums of complexity.” Recommended Lawyers: David Guadagnoli, Amy Sheridan Environment: Transactional Fintech “Sullivan & Worcester is one of the finest firms with which I have worked.” “The lawyers are excellent, and the firm consistently provides the highest quality of customer service.” Leading Partner: Joel Telpner Recommended Lawyers: Natalie Lederman, Benjamin Armour, Scott Kaufman, Harvey Bines, Christopher Curtis Land Use/Zoning Recommended Lawyers: Gregory Sampson, Ashley Brooks, Victor Baltera, Karen Kepler, Ashley Tan M&A: Corporate and Commercial: Venture Capital and Emerging Companies Recommended Lawyers: Scott Kaufman, Lewis Segall, Benjamin Armour, Michael Student M&A: Middle-Market ($0-250m) “The partner Lewis Segall has been working with our company for 15 years and we have a good working relationship with him. He knows our history and very attentive to our needs.” “Lewis Segall is very attentive to our needs. We very much value him.” Leading Partners: Benjamin Armour, Lewis Segall Recommended Lawyers: Natalie Lederman Mutual/Registered/Exchange-Traded Funds “Sullivan & Worcester's practice is defined by its deep expertise in investment funds and its ability to deliver clear, commercially grounded advice across the full fund lifecycle—from formation and structuring to regulatory compliance and complex transactions.” “The team is highly experienced, collaborative, and excel in efficient execution and clear communication.” Leading Partner: Nicole Crum Recommended Lawyers: David Leahy, David Mahaffey, Rachael Schwartz Real Estate Leading Partner: John Steiner Recommended Lawyers: Ashley Brooks, Karen Kepler, Gregory Sampson, Sharon Leifer, Louis Monti, Spencer Stone, Ashley Tan Real Estate Investment Trusts (REITs) “We have built multiple complex and sophisticated REIT platforms over the years and worked with many top-tier REIT specialists, but Sullivan’s REIT practice is by far the best, with Sarah Wellings.” Leading Partner: Ameek Ashok Ponda Next Generation Partner: Sarah Wellings Recommended Lawyers: Angela Gomes, Louis Monti, Shu Wei, Cameron Cosby International Tax “The international collaboration with S&W is exceptional.” “What really stands out is their willingness to engage, openness to different ideas and opinions, clearly expressed expectations, and clients' objectives.” Leading Partner: Douglas Stransky Recommended Lawyers: Lewis Greenwald, Eric Rietveld Tax > US Taxes: Contentious Recommended Lawyers: Richard Jones, David Nagle, Daniel Ryan, Caroline Kupiec Tax > US Taxes: Non-Contentious “Sarah Wellings is, quite simply, the best lawyer we have ever worked with. Her expertise extends far beyond tax and REIT matters, encompassing governance, financing, and complex commercial issues. Decades of experience and technical mastery make her an indispensable partner. Sarah is our central point of contact who makes everything seamless. Her in-house counsel background gives her a unique client perspective: she anticipates needs, solves problems before they arise, and delivers concise, well-structured updates that simplify even the most intricate issues. She coordinates effortlessly with all parties involved. Her judgment is exceptional. Sarah strikes the perfect balance between comprehensive academic rigor and practical, business-oriented advice. She combines technical REIT/tax excellence with commercial instincts, ensuring every recommendation is both legally sound and strategically smart. Her ability to translate complex law into clear, actionable guidance is unmatched. Sarah is incredibly responsive without ever sacrificing quality. She treats our matters as her own, demonstrating a rare ownership mindset and collaborative spirit. Her integrity is uncompromising, giving us absolute confidence in her counsel. In short, Sarah Wellings defines legal excellence: reliable, commercially minded, and client-focused. Working with her feels like being in the safest possible hands; she consistently exceeds expectations and orchestrates complex transactions with clarity and precision.” Recommended Lawyers: Ameek Ashok Ponda, Richard Jones, Douglas Stransky, Sarah Wellings About Sullivan Sullivan & Worcester (Sullivan) is a premier international law firm with lawyers in Boston, London, New York, Tel Aviv and Washington, D.C. Sullivan’s clients, including Fortune 500 companies, leading financial services firms and asset managers, boards of directors, real estate companies, and emerging businesses, rely on Sullivan’s ability to navigate complex legal and operational landscapes, the impeccable judgment of its lawyers, and its commitment to best-in-class client service.

Natalie S. Lederman

Natalie S. Lederman

Natalie S. Lederman

Natalie, a corporate partner, leads Sullivan's Fintech & Blockchain Group. She represents a diverse base of clients, including public and private companies, domestic and international, in a broad range of business and finance matters with a focus on cross-border mergers and acquisitions, securities law compliance, joint venture and financing transactions (including multi-jurisdictional trade and export finance transactions) and governance.

She represents companies across various industries, including finance, technology, media, energy, sports, healthcare, manufacturing and design. Additionally, Natalie has unique experience in advising dozens of blockchain and digital asset businesses of various sizes on complex regulatory challenges. She advises her clients in the formation and development of digital asset and cryptocurrency-based companies and technologies, on token, NFT and other digital asset sales, other generation and distribution events, and market infrastructure and exchange solutions on distributed ledger technology. She also counsels clients on domestic and cross-border cutting-edge distributed ledger and cryptocurrency, fintech and other consumer finance transactions.

Clients also benefit from Natalie's experience in litigating matters arising out of complex corporate and financial transactions and contractual disputes. Her IP experience includes preparing various intellectual property agreements (including purchases, assignments and licensing agreements), and she has counseled clients regarding selection and maintenance of trademarks, as well as copyright and domain name issues.

Natalie also currently serves as the Chair of Sullivan's Hiring Committee, and previously served as Director of Sullivan’s Summer Associate Program.

Prior to practicing law, Natalie was a financial consultant with Deloitte LLP in New York, advising national leadership on strategy initiatives, mergers and acquisitions.

Viewpoints
All Viewpoints
CFTC Outlines Contemplated Comprehensive Regulatory Framework for Retail Crypto Asset Transactions
On October 13, 2026, the Commodity Futures Trading Commission (the “CFTC”) issued an advance notice of contemplated rulemaking outlining two related initiatives concerning retail crypto asset transactions under Section 2(c)(2)(D) of the Commodity Exchange Act (the “CEA”). The first, referred to as Regulation CTX, sets out the CFTC’s preliminary interpretations of when crypto asset transactions are offered on a leveraged, margined or financed basis and when those transactions result in “actual delivery.” The second, referred to as Regulation CAM, describes a contemplated regulatory framework for trading venues and intermediaries handling covered transactions. If ultimately adopted substantially as contemplated, the initiatives could expand the circumstances in which crypto asset transactions are subject to federal commodities regulation and create a new regulatory pathway for crypto asset trading platforms seeking to operate under CFTC supervision. Background A Section 2(c)(2)(D) transaction is any transaction in a commodity that is both “(I) entered into with, or offered to (even if not entered with), a person that is not an eligible contract participant or eligible commercial entity" and "(II) entered into with, or offered to (even if not entered with), on a leveraged or margined basis, or financed by the offeror, the counterparty, or a person acting in concert with the offeror or counterparty on a similar basis.”  Unless an exception applies, Section 2(c)(2)(D) subjects such transactions to specified provisions of the CEA as if they were futures contracts and generally requires them to be conducted on or subject to the rules of a CFTC-regulated exchange. The CFTC contends that uncertainty surrounding the application of Section 2(c)(2)(D) to digital assets has impeded the migration of crypto trading activity to federally regulated markets.  According to the CFTC, retail market participants have instead relied primarily on state-level regulatory frameworks that were developed for money transmission activities rather than for trading markets.  The CFTC’s proposal seeks to replace that fragmented approach with a federal framework focused on market integrity, customer protection, transparency and risk management. Regulation CTX Regulation CTX, as described in the advance notice, contemplates a new comprehensive interpretation of how Section 2(c)(2)(D) applies to crypto asset transactions, following the CFTC’s withdrawal in 2025 of its prior interpretive guidance concerning actual delivery of digital assets. The advance notice focuses principally on two threshold issues: (a) when a transaction is deemed to be offered on a leveraged, margined or financed basis, and (b) when a crypto asset transaction is deemed to result in "actual delivery" sufficient to fall outside Section 2(c)(2)(D).  The advance notice reflects the CFTC's view that a broad range of crypto asset transactions currently conducted on spot trading platforms may fall within the scope of Section 2(c)(2)(D) and therefore may be subject to a federal regulatory framework comparable to that applicable to futures transactions. Broad Interpretation of "Offer" Perhaps the most consequential aspect of Regulation CTX is the CFTC's contemplated interpretation of what constitutes an "offer" of leverage, margin or financing. The CFTC preliminarily concludes that a transaction may become subject to Section 2(c)(2)(D) not only when leverage is actually utilized, but whenever a retail customer is offered the ability to obtain leverage, margin or financing, regardless of whether the customer ultimately elects to transact on a fully paid basis.  Thus, a covered offer may arise through a variety of customer-facing arrangements, including account opening documentation, exchange terms and conditions, margin agreements, financing programs and similar contractual arrangements that make leverage available to customers. The CFTC also suggests that financing arrangements offered through affiliated or coordinated third parties could trigger Section 2(c)(2)(D) treatment.  The CFTC also preliminarily concludes that financing offered by a third party may constitute a covered offer where the arrangement is facilitated, arranged, endorsed or materially assisted by the offeror or counterparty, including through marketing, influence over financing terms, revenue-sharing arrangements or integration with the offeror’s platform. Interpretation of the Actual Delivery Exception The advance notice also addresses the scope of the "actual delivery" exception in the context of in the application of Section 2(c)(2)(D) to digital assets.  The “actual delivery” exception excludes from Section 2(c)(2)(D) certain contracts that result in actual delivery and reflects typical cash market activity rather than the economic substance of an open futures contract.  In short, it reflects Congress’s intent not to interfere in the spot markets.  In the advance notice, the CFTC preliminarily concludes that actual delivery requires the customer to obtain a meaningful degree of possession or control over the purchased crypto asset. Depending on the asset and transaction, a meaningful degree of possession or control may require the customer to possess the credentials, such as private keys, associated with the relevant wallet address or account. Where an asset carries governance, staking or similar rights, the CFTC suggests that meaningful possession and control may also require the customer to exercise those rights directly and without material intermediary restrictions.  Under the CFTC’s preliminary interpretation, a fully paid, open CTX that remains reflected only through an exchange’s internal book-entry system would generally remain subject to Section 2(c)(2)(D) until actual delivery or another statutory exception applies. Continued Regulation of Fully Paid Positions The CFTC also takes the preliminary position that a fully paid crypto asset transaction may remain subject to Section 2(c)(2)(D) until actual delivery occurs. As a result, crypto assets held through an exchange's custodial or book-entry system, rather than transferred to a customer-controlled wallet, could remain within the scope of the CFTC's regulatory authority notwithstanding that the customer has paid the full purchase price.  Conversely, the CFTC acknowledges that many transactions executed through on-chain protocols may naturally satisfy the actual-delivery requirement because settlement occurs directly to customer-controlled wallets and results in the customer obtaining meaningful possession and control of the acquired assets.  Taken together, the contemplated interpretations of “offer,” “actual delivery” and fully paid positions would significantly broaden the circumstances in which crypto asset transactions may become subject to CFTC regulation. Regulation CAM Regulation CAM, as described in the advance notice, contemplates a new federal regulatory framework for crypto asset trading venues that offer transactions subject to Section 2(c)(2)(D). Rather than requiring digital asset platforms to fit within regulatory structures developed for traditional futures markets, the advance notice would create a specialized subset of designated contract market registration designed specifically for crypto asset transactions while preserving core principles relating to customer protection, financial integrity, market surveillance and risk management. Creation of a New Crypto Asset Market Registration Category Under the advance notice, a registered "Crypto Asset Market" ("CAM") would operate as a specialized form of designated contract market subject to modified regulatory requirements intended to accommodate the commercial realities of digital asset trading. The CFTC contemplates a framework that would permit, among other things, continuous 24-hour trading, integration of blockchain technologies into trading and market infrastructure, crypto-specific disclosure and surveillance requirements, specialized custody and operational standards, and the use of technology-enabled compliance controls. In developing the CAM framework, the CFTC repeatedly emphasizes the need to balance innovation and technological flexibility with traditional regulatory objectives such as customer protection, market transparency, prevention of manipulation and operational resilience. As currently contemplated, CTXs conducted on a CAM would be intermediated by an FCM and cleared and settled through a DCO, although the CAM, futures commission merchant (FCM) and derivatives clearing organization (DCO) functions could be performed by affiliated entities or, subject to appropriate registrations and safeguards, combined within a single integrated organization. Acceptance of Vertically Integrated Market Structures A particularly significant aspect of the advance notice is the CFTC’s willingness to accommodate vertically integrated business models that are commonly used in digital asset markets. Unlike traditional market structures that often separate trading, brokerage, custody and clearing functions among different regulated entities, the advance notice contemplates that a CAM could itself register as, or be affiliated with, a FCM and/or a DCO. Specialized Margin and Financing Framework The advance notice also would establish a framework for retail leveraged crypto asset transactions. Under the contemplated regime, retail customers would be permitted to obtain financing through arrangements administered by registered FCMs or qualifying banking institutions sponsored by FCMs. Those financing arrangements would serve as the basis for leveraged crypto asset transactions conducted on a CAM. Recognizing the volatility and operational characteristics of digital asset markets, the CFTC is considering a tailored margin regime rather than simply importing existing futures margin requirements. Among the subjects specifically identified for comment are continuously monitored margin systems, automated liquidation mechanisms, smart-contract-based risk management tools, standards governing acceptable collateral and rules addressing the treatment of customer assets securing financing arrangements. Custody, Customer Protection and Insolvency Issues The advance notice likewise devotes substantial attention to customer asset protection and raises numerous questions regarding how customer assets should be safeguarded within the CAM structure. In particular, the CFTC requests comment regarding customer asset segregation, rehypothecation practices, proof-of-reserves frameworks, custody arrangements, insolvency protections and the treatment of customer assets in the event of an intermediary bankruptcy.  The advance notice reflects the CFTC’s willingness to consider significant modifications to existing regulatory requirements governing exchange, brokerage, custody and clearing functions where necessary to accommodate the technological and operational characteristics of crypto asset markets, while preserving customer-protection, risk-management and market-integrity objectives. Sullivan Observations Convergence of Traditional and Digital Asset Market Infrastructure. The advance notice does not simply seek to regulate existing crypto trading activity.  Rather, it adapts core concepts of the CEA to digital asset markets, including exchange regulation, intermediary oversight, customer protections, clearing and margin requirements.  As a result, the advance notice may lower regulatory barriers for traditional financial institutions that have been reluctant to participate in digital asset markets while simultaneously imposing a more institutional regulatory framework on existing crypto market participants.   Expansion of CFTC Jurisdiction and Reorientation of Market Structure Regulation. Although framed as an interpretive and rulemaking initiative, the advance notice would significantly expand the practical reach of the CFTC's authority over crypto asset markets. The contemplated interpretations of "offer" and "actual delivery" would subject many transactions that market participants have historically viewed as spot transactions to a federal regulatory framework under Section 2(c)(2)(D). More broadly, the advance notice reflects the CFTC’s view that covered trading activity should operate within a uniform federal market-structure regime, rather than remain principally dependent on state money-transmission and crypto-asset licensing frameworks. The precise extent to which federal regulation would displace particular state-law requirements, however, remains to be developed.   Part of a Broader SEC-CFTC Digital Asset Regulatory Framework. The advance notice should not be viewed in isolation. Throughout the release, the CFTC repeatedly situates Regulation CTX and Regulation CAM within a broader federal effort, undertaken jointly with the SEC, to establish a comprehensive regulatory framework for digital asset markets. The advance notice builds on the agencies' March 2026 Joint Crypto Asset Taxonomy, the SEC-CFTC memorandum of understanding regarding digital asset regulation, and the SEC's contemplated Regulation Crypto Assets (91 Fed. Reg. 54510, August 21, 2026) all of which are intended to provide greater clarity regarding the regulatory treatment of crypto assets and secondary market trading. The advance notice also reflects an increasingly consistent regulatory focus on customer asset protection and custody arrangements. While operating under different statutory frameworks, the SEC and the CFTC are examining issues such as custody, customer asset segregation, intermediary insolvency, and the safeguarding of digital assets held for customers. (See Sullivan Client Alert SEC Proposes New Crypto Custody Framework for Registered Investment Advisers and Regulated Funds.)  Market participants should expect continued regulatory scrutiny of trading, custody, financing and clearing arrangements, particularly where a single platform performs multiple functions within the digital asset ecosystem.   Potential Impact on Existing Market Structures. The advance notice may require digital asset exchanges, custodians, lenders, broker-dealers and other market participants to reevaluate custody arrangements, wallet structures, financing programs, customer onboarding documentation and affiliated business models. Platforms that offer margin or financing features may find that transactions historically viewed as spot transactions become subject to CFTC regulation unless actual delivery occurs, while integrated trading, custody and financing arrangements may face increased regulatory scrutiny. What Comes Next Public comment of the advance notice closes December 14, 2026.  As the advance notice does not contain contemplated regulatory text and leaves many central elements of both initiatives open for comment, the CFTC would need to undertake additional notice-and-comment rulemaking before adopting binding Regulation CTX or Regulation CAM requirements. For More Information This Client Alert has been prepared by John Hunt, a Partner in the Investment Management practice group, and Natalie Lederman, a Partner in and Leader of the Fintech & Blockchain practice group, of the international law firm of Sullivan & Worcester LLP.  For more information, Mr. Hunt may be reached in our Boston office by calling +1 (617) 338-2961 or our London office by calling +44 (0)20 7448 1000, or by email at jhunt@sullivanlaw.com. Ms. Lederman may be reached in our New York office by calling +1 (212) 660-3039 or by email at nlederman@sullivanlaw.com. This Client Alert is provided for general informational purposes only and does not constitute legal advice.
Breaking: FinCEN Removes BOI Reporting Requirements for U.S. Companies and U.S. Persons
The U.S. Department of the Treasury’s Financial Crimes Enforcement Network (FinCEN) announced, on March 21, 2025, that it issued an interim final rule that removes the requirements for U.S. companies and U.S. persons to report beneficial ownership information (BOI) under the Corporate Transparency Act (CTA). The interim final rule narrows the existing BOI reporting requirements by revising the definition of “reporting company” (i.e., companies required to file BOI reports) to include only “foreign reporting companies” (i.e., companies formed outside of a US state or tribal territory but that are registered to do business in the United States). As a result, domestic reporting companies (i.e., companies formed in a US state or tribal territory) are now exempted from the BOI reporting requirements pursuant to the CTA. The rule also provides foreign reporting companies with exemptions from reporting any U.S. persons who are beneficial owners of the foreign reporting company. Foreign reporting companies that are registered to do business in the United States must file BOI reports with FinCEN within 30 days from the date of the rule’s publication in the Federal Register on March 26, 2025. If foreign reporting companies are registered to do business in the United States on or after the date of publication, they must submit BOI reports within 30 days after receiving notice of the effectiveness of their registration. Please see our prior CTA-related client alerts here and here for additional information about the filing requirements and the applicable exceptions, and do not hesitate to reach out to your contacts at Sullivan if you have any questions about CTA compliance or BOI report filing requirements.
Sullivan Advises BAFT and ITFA on Updated CRR Legal Opinions for the 2008 English Law Master Participation Agreement (MPA)
(London and New York) – Sullivan has advised BAFT (the Bankers Association for Finance & Trade) and ITFA (the International Trade and Forfaiting Association) on the publication of the two Capital Requirements Regulation (CRR) legal opinions covering the 2008 English law Master Participation Agreement (MPA). The newly released opinions comprise the EU CRR opinion on English law MPA 2008 and the UK CRR opinion on English law MPA 2008. They are intended for institutions that continue to use the 2008 version of the MPA, having executed it prior to the introduction of the later versions. The publication of these two legal opinions completes the suite of updated CRR legal opinions that Sullivan has prepared for BAFT and ITFA, following the release of the updated opinions covering the other English law MPAs, New York law MPAs and the Surety MPAs earlier this year, which can be read in full, here. Importantly, these opinions note that eligibility for credit risk mitigation (CRM) may only apply if the Participant shares in the fraud risk in the optional wording of Clause 11. As the 2008 English law MPA has long since been superseded, ITFA has announced that these are the final legal opinions that will be issued in respect of that document, reflecting both the age of the underlying template and the increasing difficulty of providing a clean opinion where one of the optional wordings is adopted. Geoffrey Wynne, head of Sullivan’s Trade & Export Finance Group, commented: “We are pleased to have continued our long-standing work with BAFT and ITFA advising on these CRR legal opinions for the 2008 English law MPA. Their publication completes the current suite of opinions available to members and provides support for institutions that continue to use the earlier version of the agreement. It is hoped that institutions will pay heed to reservations and react accordingly.” The Sullivan team advising BAFT and ITFA includes partners Geoffrey Wynne and Marian Boyle in London and partner Natalie Lederman in New York. About Sullivan Sullivan & Worcester (Sullivan) is a global law firm with lawyers in Boston, London, New York, Tel Aviv and Washington, D.C. Sullivan’s clients, including Fortune 500 companies, leading financial services firms and asset managers, boards of directors and emerging businesses, rely on Sullivan’s ability to navigate complex legal and operational landscapes and its commitment to best in class client service. For further information, please visit the firm’s website and LinkedIn.
Top Tier Firm, Legal 500 United States 2026
Sullivan & Worcester Ranked in the Legal 500 United States 2026 Edition
Boston, MA – Sullivan & Worcester announced that its practice groups and attorneys have been ranked and recommended in the Legal 500 United States 2026. The firm’s Real Estate practice was newly ranked Tier 1 in the “Real estate – mid-market ($0-500m)” category and the firm maintained rankings across a variety of practice areas. Partners Nicole Crum and John Steiner were newly ranked as Leading Partners and Ryan Rosenblatt as a Next Generation Partner. Peers and more than 300,000 corporate counsel were surveyed and interviewed globally in the past 12 months to assess law firms’ overall visibility and reputation, culminating in detailed rankings and editorial. The Legal 500 is an independent guide, and firms and individuals are recommended purely on merit. Sullivan's lawyers received the following rankings: Leading Partners: The Legal 500’s Guide to Outstanding Lawyers Nationwide Benjamin Armour - M&A: Middle-Market (Sub-$500m); M&A: middle-market ($0-250m) Ameek Ashok Ponda - Real Estate Investment Trusts (REITs)  Nicole Crum - Mutual/registered/exchange-traded funds Lewis Segall - M&A: Middle-Market (Sub-$500m); M&A: middle-market ($0-250m) John Steiner - Real estate – mid-market ($0-500m) Douglas Stransky - International Tax Joel Telpner - Fintech Next Generation Partners: The Legal 500’s Guide to Up-and-Coming Lawyers Nationwide Ryan Rosenblatt - General commercial disputes – mid-market ($250-500m) Sarah Wellings - Real Estate Investment Trusts (REITs) Practice Areas Ranked and Attorneys Recognized Corporate Governance “Our lead partner, Nicole Crum, who leads the investment industry practice, is exceptional. She demonstrates strong industry knowledge yet is very personable and anticipates what we need to know or what we should consider doing to handle any matter. The team roll up their sleeves and provide recommendations as to how we as a board should handle any matter. Strong service commitment and work ethic!” “The team we have at Sullivan & Worcester has served our company for years and knows the management team, staff as well as our board members. They are extremely responsive and proactive and anticipate what we should be aware of, concerned about, excited about, and how to handle oversight, processes and protocols to ensure we are carrying out our fiduciary duties. The partners are experts in this industry.” Leading Partner: Nicole Crum Recommended Lawyers: Howard Berkenblit, David Leahy Dispute Resolution/General Commercial Disputes “Diverse skillset. Client centric. Transparency. Urgency provided on all matters.” “I have worked with Gerry Silver for over 15 years and have found his pragmatic approach to complex matters refreshing. He understands our business, culture and market, and will give me his opinion in a digestible manner.” Next Generation Partner: Ryan Rosenblatt Recommended Lawyers: Gerry Silver, Patrick Dinardo, Laura Steinberg, Michael Sullivan, Amy Zuccarello, Erika Todd, Christopher Shields, Anna Lea McNerney Employee Benefits, Executive Compensation and Retirement Plans: Design “The level of expertise is top shelf. David Guadagnoli seems to know all of ERISA and IRS rulings.” “David Guadagnoli and Amy Sheridan both have superior knowledge in their respective areas. I value the ability to raise issues whether simple or complex. The firm takes the same diligent approach across all spectrums of complexity.” Recommended Lawyers: David Guadagnoli, Amy Sheridan Environment: Transactional Fintech “Sullivan & Worcester is one of the finest firms with which I have worked.” “The lawyers are excellent, and the firm consistently provides the highest quality of customer service.” Leading Partner: Joel Telpner Recommended Lawyers: Natalie Lederman, Benjamin Armour, Scott Kaufman, Harvey Bines, Christopher Curtis Land Use/Zoning Recommended Lawyers: Gregory Sampson, Ashley Brooks, Victor Baltera, Karen Kepler, Ashley Tan M&A: Corporate and Commercial: Venture Capital and Emerging Companies Recommended Lawyers: Scott Kaufman, Lewis Segall, Benjamin Armour, Michael Student M&A: Middle-Market ($0-250m) “The partner Lewis Segall has been working with our company for 15 years and we have a good working relationship with him. He knows our history and very attentive to our needs.” “Lewis Segall is very attentive to our needs. We very much value him.” Leading Partners: Benjamin Armour, Lewis Segall Recommended Lawyers: Natalie Lederman Mutual/Registered/Exchange-Traded Funds “Sullivan & Worcester's practice is defined by its deep expertise in investment funds and its ability to deliver clear, commercially grounded advice across the full fund lifecycle—from formation and structuring to regulatory compliance and complex transactions.” “The team is highly experienced, collaborative, and excel in efficient execution and clear communication.” Leading Partner: Nicole Crum Recommended Lawyers: David Leahy, David Mahaffey, Rachael Schwartz Real Estate Leading Partner: John Steiner Recommended Lawyers: Ashley Brooks, Karen Kepler, Gregory Sampson, Sharon Leifer, Louis Monti, Spencer Stone, Ashley Tan Real Estate Investment Trusts (REITs) “We have built multiple complex and sophisticated REIT platforms over the years and worked with many top-tier REIT specialists, but Sullivan’s REIT practice is by far the best, with Sarah Wellings.” Leading Partner: Ameek Ashok Ponda Next Generation Partner: Sarah Wellings Recommended Lawyers: Angela Gomes, Louis Monti, Shu Wei, Cameron Cosby International Tax “The international collaboration with S&W is exceptional.” “What really stands out is their willingness to engage, openness to different ideas and opinions, clearly expressed expectations, and clients' objectives.” Leading Partner: Douglas Stransky Recommended Lawyers: Lewis Greenwald, Eric Rietveld Tax > US Taxes: Contentious Recommended Lawyers: Richard Jones, David Nagle, Daniel Ryan, Caroline Kupiec Tax > US Taxes: Non-Contentious “Sarah Wellings is, quite simply, the best lawyer we have ever worked with. Her expertise extends far beyond tax and REIT matters, encompassing governance, financing, and complex commercial issues. Decades of experience and technical mastery make her an indispensable partner. Sarah is our central point of contact who makes everything seamless. Her in-house counsel background gives her a unique client perspective: she anticipates needs, solves problems before they arise, and delivers concise, well-structured updates that simplify even the most intricate issues. She coordinates effortlessly with all parties involved. Her judgment is exceptional. Sarah strikes the perfect balance between comprehensive academic rigor and practical, business-oriented advice. She combines technical REIT/tax excellence with commercial instincts, ensuring every recommendation is both legally sound and strategically smart. Her ability to translate complex law into clear, actionable guidance is unmatched. Sarah is incredibly responsive without ever sacrificing quality. She treats our matters as her own, demonstrating a rare ownership mindset and collaborative spirit. Her integrity is uncompromising, giving us absolute confidence in her counsel. In short, Sarah Wellings defines legal excellence: reliable, commercially minded, and client-focused. Working with her feels like being in the safest possible hands; she consistently exceeds expectations and orchestrates complex transactions with clarity and precision.” Recommended Lawyers: Ameek Ashok Ponda, Richard Jones, Douglas Stransky, Sarah Wellings About Sullivan Sullivan & Worcester (Sullivan) is a premier international law firm with lawyers in Boston, London, New York, Tel Aviv and Washington, D.C. Sullivan’s clients, including Fortune 500 companies, leading financial services firms and asset managers, boards of directors, real estate companies, and emerging businesses, rely on Sullivan’s ability to navigate complex legal and operational landscapes, the impeccable judgment of its lawyers, and its commitment to best-in-class client service.